Florida Real Estate Investment Guide 2026: Top Cities for Property Investors
Florida real estate investment guide 2026
Florida has no shortage of places to buy property. Finding one that actually fits your numbers is the harder part. A downtown Miami condo and a three-bedroom home in Cape Coral can both be called investment properties, but they operate like completely different businesses. The rent, insurance, association rules and likely buyer at resale are rarely comparable.
For 2026, the smart approach is to match a city to a strategy, then test a specific address. You might want steady year-round tenants, a property you can occasionally use, a luxury asset to hold over time, or a smaller home that needs less capital to enter. None of those goals automatically points to the same city.
This guide compares seven Florida investment markets using publicly available market context and the practical costs investors need to check. For more Florida real estate insights, explore the U.S. Prime Realty blog.
Quick answer: Orlando and Tampa are sensible starting points for investors studying traditional, year-round rentals; Cape Coral and Fort Myers offer Southwest Florida single-family opportunities; Jacksonville can provide lower advertised entry prices; Miami may suit higher-budget, highly selective condo or urban-rental strategies; and Naples is better approached as a premium lifestyle or long-hold market. These are research starting points, not guaranteed rankings or returns.
What is in this guide
- Florida Investment Property Market: What Changed in 2026
- Top Florida Cities for Property Investors at a Glance
- 1. Orlando: A Practical Starting Point for Long-Term Rentals
- 2. Tampa: Rental Demand Depends on the Neighborhood
- 3. Cape Coral: Single-Family Rentals and a Waterfront Premium
- 4. Fort Myers: Look Closely at the Property, Not Just the Price
- 5. Jacksonville: Screen for Affordability, Then for Durability
- 6. Miami: Selective Opportunities, Especially in Condos
- 7. Naples: Premium Assets, Different Return Expectations
- Which Florida City Fits Your Investment Strategy?
- How to Calculate a Florida Rental Property’s Real Return
- Long-Term Rental vs. Vacation Rental vs. Pre-Construction
- The 2026 Investor Due-Diligence Checklist
- Florida Property Tax and Rental Income: Two Important Reminders
- How U.S. Prime Realty Helps You Compare Investment Properties
- Frequently Asked Questions About Florida Real Estate Investing in 2026
Florida Investment Property Market: What Changed in 2026
Florida Realtors reported a September 2026 statewide median existing single-family sale price of $415,000, up 1.2% year over year. The condo-townhouse median was approximately $293,500, down 1.8%. Supply differed as well: 4.4 months for single-family homes versus 7.7 months for condos and townhouses. That contrast matters: an investor considering a condo should not assume that a detached home across town faces the same competition or resale conditions.
The statewide figures are a directional benchmark, not a substitute for local comparable sales. Source: Florida Realtors September and Q3 2026 market release.
Top Florida Cities for Property Investors at a Glance
| City / market | Where to focus | Investment caution |
|---|---|---|
| Orlando | Traditional rentals; suburban townhomes / houses | New-build competition; HOA/CDD and actual tenant demand |
| Tampa | Workforce and suburban long-term rentals | Micro-market variability; flood and storm exposure |
| Cape Coral | Detached homes; selective canal / waterfront assets | Flood, wind, seawalls and rental underwriting |
| Fort Myers | Year-round residential rentals; select value-add | Condition, storm history and neighborhood-level rent |
| Jacksonville | Lower-entry-price rental screening | Block-by-block rents, repairs and vacancy |
| Miami | Urban rentals; selected condos; higher-budget holds | Condo budgets, rental restrictions and financing |
| Naples | Premium homes; luxury or seasonal strategies | Higher carrying costs and seasonality |
Comparison note: The categories above describe possible strategies, not a claim that any city guarantees appreciation, occupancy or positive cash flow.
1. Orlando: A Practical Starting Point for Long-Term Rentals
Orlando belongs on the shortlist when you want a property designed around ordinary monthly rent rather than a vacation-rental projection. Its employment and residential footprint extend well beyond the theme-park corridor. A townhouse serving a year-round household should be analyzed differently from a home marketed around tourism.
Where Orlando Investors Should Look
Compare established neighborhoods with suburban areas where builders are delivering new homes. Pay attention to employers, driving time, lease comparables for the exact floor plan and how many similar properties are competing for tenants. Some newer communities carry HOA or community development district (CDD) charges that can take a meaningful bite out of cash flow.
Investor fit: a buy-and-hold investor prepared to verify achievable rent, fees and property management. Watch-out: buying a new home on the assumption that every nearby household will pay a premium.
2. Tampa: Rental Demand Depends on the Neighborhood
Tampa offers a mix of older residential neighborhoods, suburban single-family homes and condos. The appeal is flexibility, but that is also the trap: a property close to an employment center may have a completely different tenant pool and expense profile from a coastal-area unit or far-out suburban build.
How to Underwrite Tampa
Check recent leased comparables, commute patterns, major repairs, property taxes after purchase, insurance and flood-zone exposure. For condos, read the actual association budget, reserves and lease policy before projecting rent. For houses, price the roof, HVAC and other capital expenses rather than treating them as one-off surprises.
Investor fit: a patient buyer comparing several specific neighborhoods. Watch-out: headline gross yields that exclude meaningful property costs.
3. Cape Coral: Single-Family Rentals and a Waterfront Premium
Cape Coral deserves its own analysis because a canal home is not interchangeable with an off-water rental. Waterfront access can change both what buyers pay and what future renters value. It can also add substantial maintenance liability, from docks to seawalls, and heighten the importance of location-specific flood and insurance analysis.
Our Cape Coral Investment Property: 2026 Insider Guide breaks down the difference between off-water, freshwater-canal and Gulf-access properties, along with ZIP-level questions and ownership costs.
The Cape Coral Investor Test
Ask whether you are buying for monthly income, long-term land or waterfront scarcity, or your own future use. Those are different theses. Never underwrite a Gulf-access premium without verifying bridges, canal depth, seawall condition, flood history and what a comparable property actually rents for.
Investor fit: buyers who understand Southwest Florida and can hold through market cycles. Watch-out: assuming a picturesque canal automatically delivers strong net returns.
4. Fort Myers: Look Closely at the Property, Not Just the Price
Fort Myers may appeal to investors who want a single-family rental or a smaller-value-add project without moving into Miami price tiers. Neighborhood and building condition do most of the work here. Two houses with similar list prices can produce very different results once you account for past storm repairs, roof age, elevation and tenant turnover.
Compare actual local leases, not statewide rent averages. Confirm permits for major work and seek insurance quotes before deadlines make the decision expensive. A property with a tempting purchase price can still be the costlier investment after rehabilitation and annual carrying costs.
5. Jacksonville: Screen for Affordability, Then for Durability
Jacksonville gives investors another place to look for lower advertised entry prices, particularly outside the premium waterfront and newer-home segments. But a lower purchase price is only useful when the neighborhood has sustainable rental demand and the home is not quietly accumulating repair costs.
Start with stable tenant demand, realistic vacancy assumptions and evidence of comparable leased homes. Compare property taxes and insurance on the actual address. For older houses, get a thorough inspection and budget for a roof, plumbing or electrical work that may not appear in the listing photos.
Investor fit: investors prioritizing acquisition budget and conventional leases. Watch-out: choosing purely by price-to-rent ratios while ignoring maintenance and tenant turnover.
6. Miami: Selective Opportunities, Especially in Condos
Miami is often the first city people mention when they think about Florida real estate investing. It is also a market where impressive rent numbers can distract from the full ownership cost. A condo association may control minimum lease periods, application approvals and the number of leases allowed; the building’s budget, reserves and special assessments can matter as much as the floor plan.
Before buying a rental condo, read our South Florida Condo vs. Single-Family Home: 2026 Cost Guide. It explains why condo dues, insurance, reserves and rental rules belong in the return calculation.
Investor fit: higher-capital buyers prepared to do building-level due diligence. Watch-out: underwriting a short-term-rental business before proving that the building and the city allow it.
7. Naples: Premium Assets, Different Return Expectations
Naples is better considered through the lens of lifestyle, seasonal use and high-end ownership than a promise of easy cash flow. Coastal access, building quality, association fees and the property’s exact address can outweigh broad market medians. An expensive home can be a strong personal fit while still delivering a modest income yield.
For luxury-market context, see Naples Florida Luxury Real Estate: 2026 Market Guide. It covers property-type differences, waterfront considerations and why individual neighborhoods deserve separate comparisons.
Investor fit: buyers with the resources and holding period to accommodate higher carrying costs. Watch-out: treating peak-season rents as if they recur every month of the year.
Which Florida City Fits Your Investment Strategy?
| If your priority is… | Start your research in… | Verify before an offer |
|---|---|---|
| Year-round tenants | Orlando, Tampa | Lease comps, jobs/commutes, HOA/CDD |
| Single-family / Southwest Florida | Cape Coral, Fort Myers | Flood, insurance, roof, repairs |
| Lower acquisition budget | Jacksonville | Neighborhood rents, vacancy, major systems |
| Urban condo investment | Miami | Association finances, permitted leases |
| Premium lifestyle hold | Naples | Carrying costs, seasonality, exit buyer |
How to Calculate a Florida Rental Property’s Real Return
An attractive listing can look good until the operating expenses arrive. Rather than asking only what the property might rent for, separate the income calculation into three steps: realistic annual rent, net operating income and cash flow after financing.
A Sample Rental Property Calculation
ILLUSTRATIVE EXAMPLE ONLY — not a city forecast, current listing or investment projection: A house rents for $2,200 per month and is occupied for 11 months. Collected rent is $24,200. Assume property taxes $3,500, insurance $3,600, maintenance reserve $1,800, property management $2,178 and other fees $900. Net operating income (NOI) is $12,222 before mortgage payments and income taxes. On a hypothetical $300,000 purchase, that is a 4.07% unlevered cap rate. Annual financing payments must then be deducted to estimate cash flow.
Formula: NOI = collected rental income – ordinary operating expenses (not mortgage principal or interest). Cap rate = NOI ÷ purchase price. Cash-on-cash return = annual pre-tax cash flow ÷ actual cash invested. Use real quotes and lease evidence in place of every sample number.
Costs Florida Investors Should Never Skip
- Property taxes after transfer: do not assume the seller’s homestead-related bill is your investment-property bill.
- Insurance: obtain property-specific homeowners or dwelling coverage quotes; quote flood coverage separately where relevant.
- Maintenance and capital reserves: roof, AC, appliances, pools, docks or seawalls can materially change ownership costs.
- Management, leasing and vacancy: even self-managed properties require your time and a plan for turnover.
- HOA, condo and CDD charges: ask about budgets, dues, assessments and lease restrictions.
- Financing and closing costs: use actual loan terms, lender fees, insurance requirements and cash-to-close figures.
For insurance budget context, read Florida Home Insurance in 2026. For flood exposure, use our Florida Flood Zones Guide and the FEMA Flood Map Service Center.
Long-Term Rental vs. Vacation Rental vs. Pre-Construction
A long-term rental generally starts with month-to-month affordability and stable tenant demand. A vacation rental requires a different operating model: occupancy swings, cleaning, furnishings, platform or booking costs, permits, taxes, management and weather-related cancellations. Local ordinances, condo documents and HOA rules may sharply limit short-term rentals. Never assume a listing’s “Airbnb potential” means that use is legal or viable.
Pre-construction may offer a different entry timeline but adds delivery, contract, deposit and financing uncertainty. See our Pre-Construction Homes in Florida: 2026 Buyer’s Guide before making a reservation.
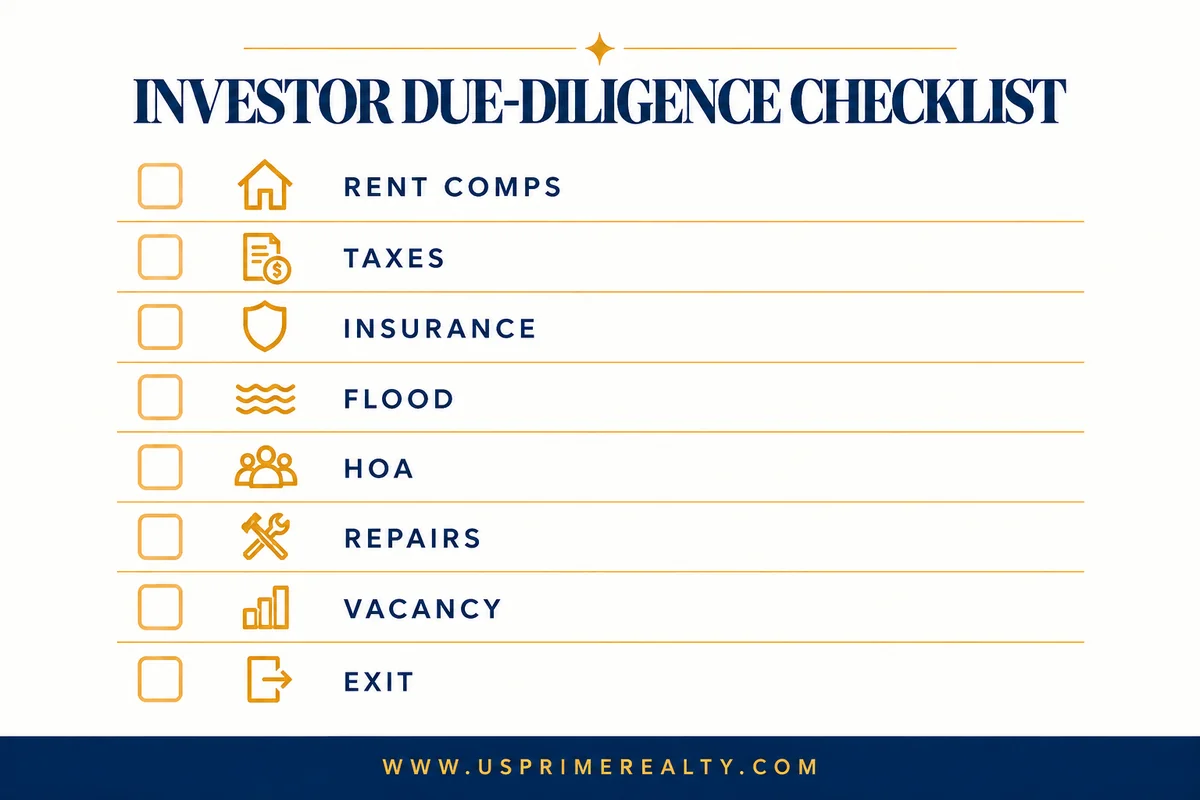
The 2026 Investor Due-Diligence Checklist
The best investment search becomes much easier when every finalist answers the same questions. Before an offer, make sure you can document:
- Three to five truly comparable recent leases and a supportable rent range.
- The property-specific insurance premium, deductible, flood exposure and prior loss / repair history.
- Post-purchase property-tax estimate from the county property appraiser.
- Association finances, upcoming assessments, rental rules and approvals (if applicable).
- Inspection findings, permit records and near-term capital work.
- Vacancy, management, leasing, maintenance and reserve assumptions.
- Local short-term-rental licensing and zoning rules if that is your intended strategy.
- An exit scenario based on comparable resale demand—not assumed annual appreciation.
Florida Property Tax and Rental Income: Two Important Reminders
A Florida investment home is not automatically eligible for the same homestead benefits a qualifying primary residence may receive. Re-estimate the property tax bill after sale instead of copying the owner’s current tax amount into your spreadsheet. For federal taxes, rental income, expenses and depreciation follow detailed rules, and personal use of a vacation property can change the treatment. Ask a qualified tax professional to apply those rules to your situation.
Official references: Florida Department of Revenue property-tax exemptions and IRS Publication 527 — Residential Rental Property.
How U.S. Prime Realty Helps You Compare Investment Properties
The right purchase is not always in the city with the loudest headlines. It is the property where the asking price, rental evidence, physical condition, ownership costs and your time horizon line up. U.S. Prime Realty can help you compare Florida neighborhoods, search available properties, organize the right property questions and coordinate with lenders, inspectors, attorneys and other licensed specialists when needed.
Thinking about buying an investment property in Miami, Orlando, Tampa, Naples, Cape Coral or Fort Myers? Call U.S. Prime Realty at 239-513-0011 or email cc@usprimerealty.com. Tell us your preferred market, budget and whether you are prioritizing cash flow, long-term appreciation potential or personal use. Buy. Sell. Invest.
Frequently Asked Questions About Florida Real Estate Investing in 2026
What is the best city to buy investment property in Florida in 2026?+
What is the best city to buy investment property in Florida in 2026?
There is no single best city. Orlando and Tampa are practical long-term rental research markets; Cape Coral and Fort Myers suit investors evaluating Southwest Florida houses; Jacksonville deserves entry-price screening; and Miami and Naples call for different condo or premium-asset analysis. The better choice depends on the property-level numbers.
Is Florida real estate still a good investment in 2026?+
Is Florida real estate still a good investment in 2026?
It may be for a carefully selected property, but not every purchase produces positive cash flow. Test real rents against taxes, insurance, fees, repairs, financing and vacancy, and consider downside scenarios before buying.
Is Miami or Orlando better for rental property?+
Is Miami or Orlando better for rental property?
Orlando may suit investors studying conventional year-round tenants and houses or townhomes. Miami can appeal to buyers interested in urban locations or condos, but association expenses and rental limits require especially close review.
Can I use a Florida investment property as an Airbnb?+
Can I use a Florida investment property as an Airbnb?
Only if the specific property complies with city or county rules, licensing and tax requirements, and any HOA or condo restrictions. Confirm all permissions in writing before basing a purchase on short-term rental income.
What expenses reduce Florida rental property cash flow?+
What expenses reduce Florida rental property cash flow?
Property taxes, insurance, flood coverage when needed, management, leasing, vacancy, repairs, capital replacement, HOA or condo fees and debt service can all reduce cash flow.
Are Florida rental property taxes the same as the current owner’s taxes?+
Are Florida rental property taxes the same as the current owner’s taxes?
Not necessarily. The seller may have homestead exemptions or assessment limitations that do not apply to an investment buyer. Request a post-transfer estimate from the county property appraiser.
Should I choose a condo or a house for investment?+
Should I choose a condo or a house for investment?
Compare the specific units and buildings. Condos can have lower asking prices but higher shared fees, assessments and lease restrictions. Houses place more repair responsibility directly on the owner.
Can U.S. Prime Realty help an out-of-state investor?+
Can U.S. Prime Realty help an out-of-state investor?
Contact U.S. Prime Realty with a budget, target city and investment approach. The team can help with property searches and local comparison while specialized legal, financing and tax matters go to qualified professionals.
Important information: City recommendations describe strategy fit rather than projected returns. Statewide market figures refer to September 2026; rental market estimates vary by provider and reporting period. U.S. Prime Realty is a real estate brokerage, not a lender, insurance agency, legal advisor or tax advisor.
Share This
About The Author
Isbely Glazer - Founder and Broker of U.S. Prime Realty
Isbely brings over 20 years of experience across Florida’s key markets. She leads with a client-first approach, combining deep market insight with a commitment to trust, results, and long-term relationships.
Business Info


Recent Posts

Moving to Florida in 2026: Why Homebuyers Continue to Choose the Sunshine State
Moving to Florida in 2026? Explore housing prices, taxes, lifestyle, top cities and hidden ownership costs before buying a Florida home.
What’s it really like to live in Orlando, Florida? The 2026 Guide
Moving to Orlando in 2026? Compare home prices, daily costs, neighborhoods, commutes, summer weather and the tradeoffs of living beyond the theme parks.
Orlando Florida Luxury Real Estate: 2026 Market Guide
Explore Orlando Florida luxury real estate in 2026: prices, Windermere, Winter Park, Lake Nona, 2026 housing data, lakefront costs and buyer tips.